

The companies we deep dived in 2025 generally performed well. For the second half of 2025, I published 5 deep dives, bringing our total deep dives to 9 for 2025. FactSet, written in 2025 but published in the first week of 2026 (due to the Christmas period), would have made this 10.
While I prefer to judge these deep dives after five years in line with my long-term holding period, it’s always worth tracking how they perform semiannually. It’s also important for you the reader to ensure you get your value for money from a subscription.
The H2 2025 company deep dives
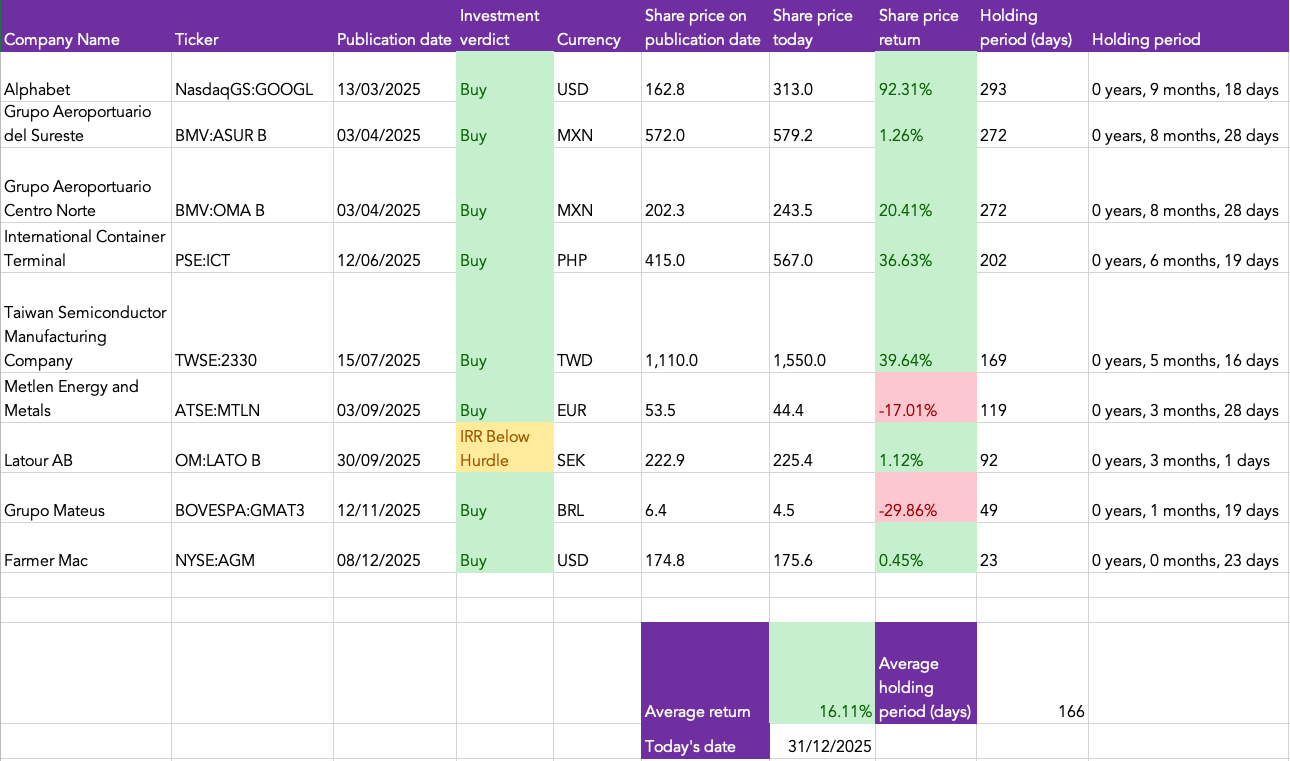
I will highlight the share price performance and fundamentals (quality, growth and value) to track how the companies are performing. For the share price performance, the table below includes the following indicators:
Deep dive publication date for each company
Investment verdict in the publication (buy or wait - only Latour AB wasn’t a buy decision due to its valuation)
Holding period in number of days and in years, months and days (final two columns)
The average return across all deep dives.
From the table above, a few things we can observe:
Performance: Of the 9 companies, 7 of them gained in share price between when I published their deep dive and the end of the year, while 2 (Metlen and Grupo Mateus) declined in share price.
Holding period: The holding period between when the company deep dive was published and the last day of 2025 averaged 166 days or 5.5 months. During this holding period, the average company share price returned +16.1%. Given the target is +15% over a 12-month period, I view this as satisfactory.
Top performers: The top performers were led by Alphabet (+92.3%), TSMC (+39.6%) and International Container Terminal (+36.7%)
Top detractors: The top detractors were Grupo Mateus (-29.9%) and Metlen (-17%).
ASUR: It’s important to note we’ll receive an additional Ps 80 per share dividend, a 14% yield in 2025, increasing its total shareholder returns.
Fundamentals update
I assess the companies from three lenses: quality, growth and value.
Quality
The table below highlights the 9 companies on five key GAAP metrics and two Jenga IP scores, sorted by earliest to latest published date:
The Jenga IP Quality Index Rating
Jenga IP Moat Status
Return on capital
EBIT margin
Net income margin
Free cash flow margin
Net debt/EBITDA
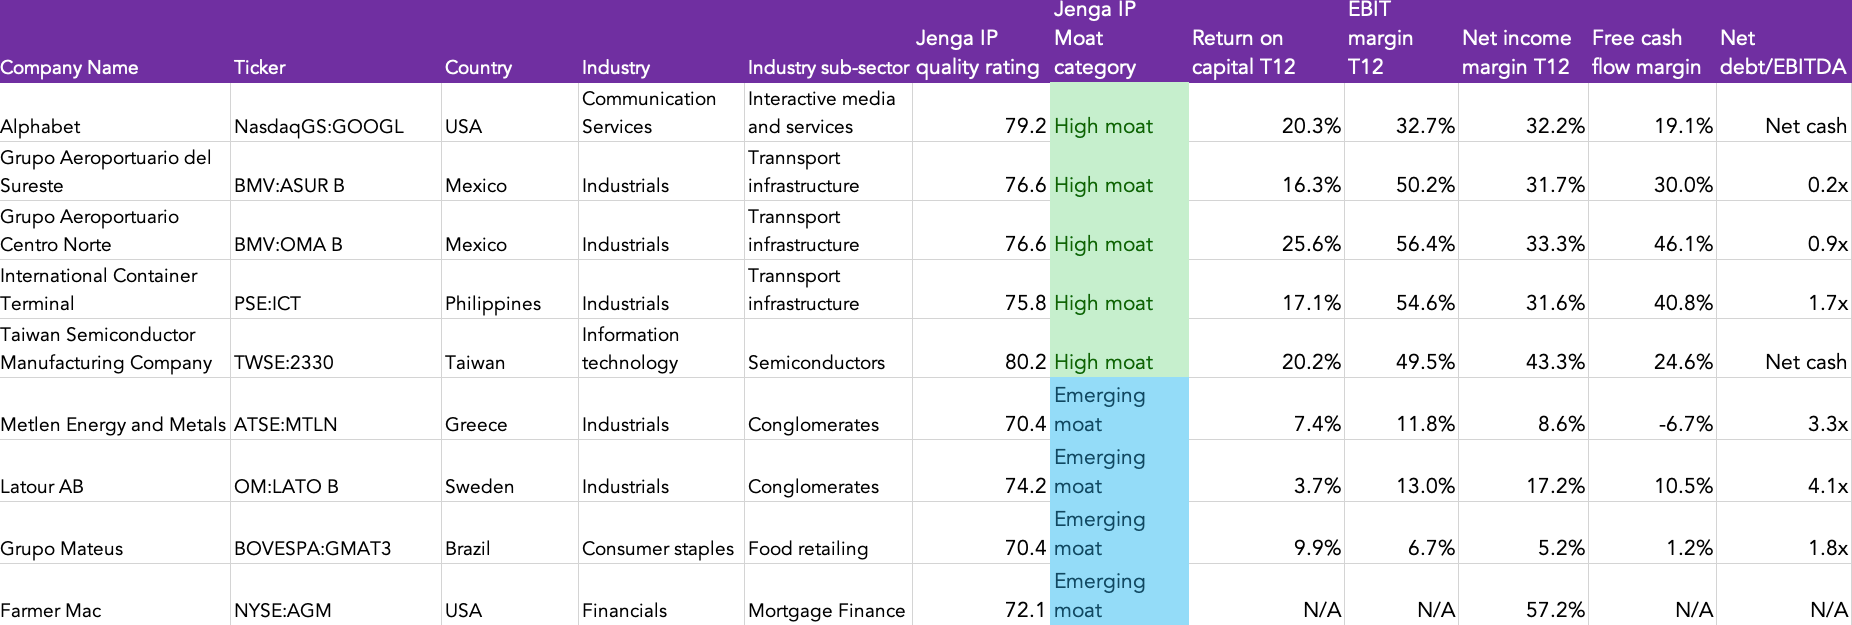
In the table above, the companies I identify as high moats (Alphabet, TSMC, OMA, ASUR and ICTSI) performed better than the emerging moats on key quality metrics such as return on capital, EBIT margin and Free cash flow margin. This is in line with our initial analysis.
Compared to our estimates, all companies, excluding Metlen and Grupo Mateus, performed in line with expectations. I view Metlen’s margins results as one-off while Grupo Mateus as slightly more prolonged, but still fixable.
On average, the 9 companies earned a net income margin of 28.9%, more than triple the S&P 500 median, with a return on capital of 15.1%, nearly double the median for the S&P 500.
Growth
1-year revenue growth
1-year EBIT growth
The Jenga IP 5-year earnings growth estimate (2024 - 2029)
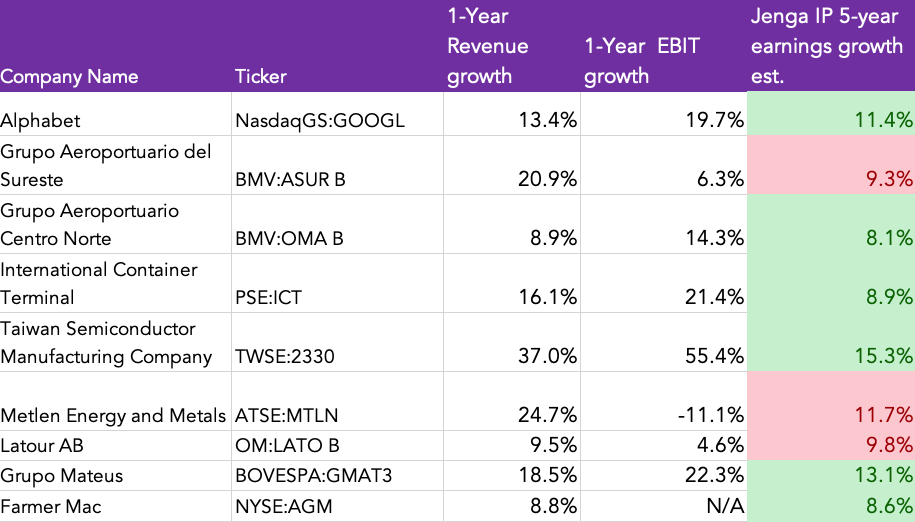
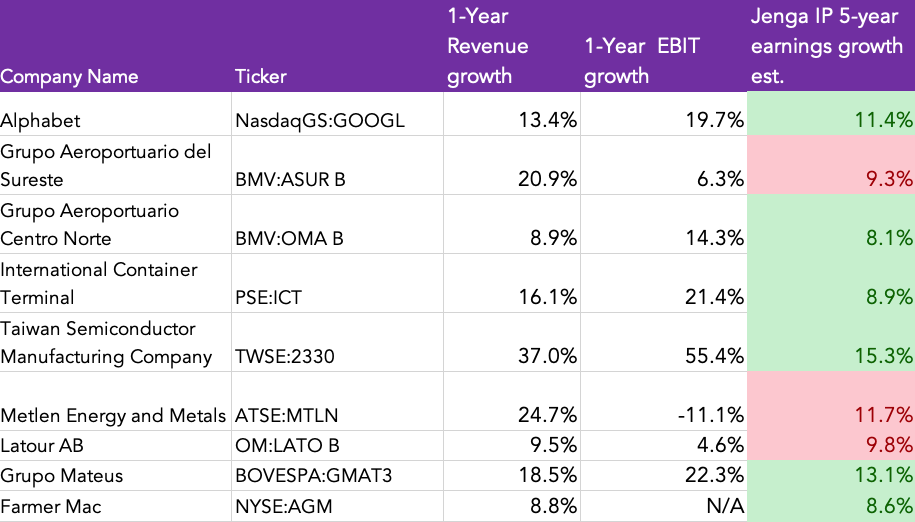
For the trailing 12 months, 6 of the 9 companies (highlighted in green) grew their EBIT faster than the 5-year earnings growth average I estimated in their deep dives. Of the 6 companies, TSMC and ICTSI were well ahead of the long-term average.
While this is generally good, many reasons could influence this, and it’s still too early to judge their long-term earnings performance, as this could simply be an earnings pull-forward.
Of the 3 companies below my growth estimate, we expected 2025 to be a challenging year for both Latour AB and ASUR, the latter having benefited from higher USD to peso exchange rates in 2024. Metlen, as mentioned earlier, is going through a one-off challenge, and I expect its earnings to reaccelerate, in line with its revenue growth for the second half of 2025.
Value
Trailing and forward EV/EBIT
Trailing and forward P/E
Jenga IP 2029 target exit multiple
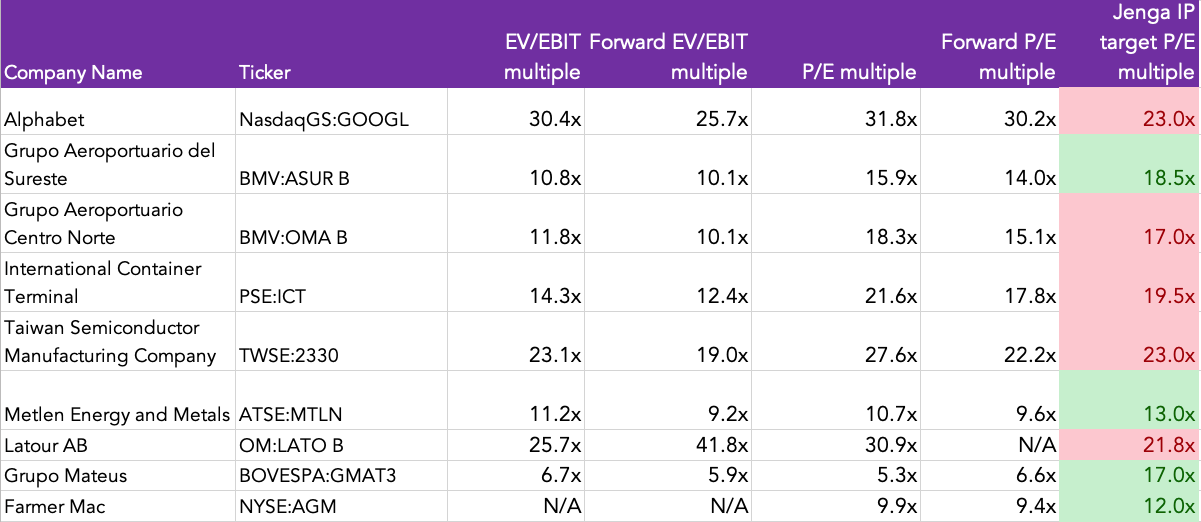
The valuations for 5 of the 9 companies are higher than our long-term average, indicating some near-term share price strength. Alphabet’s multiples increased much higher than our analysis suggested (30x forward P/E versus my long term 23x forecast), and in mid-December, I published a post explaining my reason for exiting its shares.
I continue to view TSMC and ICTSI favourably but will carefully watch their valuations in the near term. On the other side, 4 of the 9 companies continue to have favourable valuations today, particularly Grupo Mateus, and I plan on publishing a follow-on note after its many challenges in Q4 2025.
Final thoughts
Overall, I’m pleased with how the companies I published performed, but I do hope we can get even better results for 2026. As always, I remain focused on searching for high quality companies with good growth prospects, available at undervalued prices.
I had planned to publish FactSet to make 2025 10 deep dives (one per month), but on second thought, I figured it’s a bad idea
on Christmas Day, so I published its 15,000-word report earlier this week. You can now read the final deep dive here.
We’ll be kicking 2026 off with a deep dive on Visa, and I can’t wait to share the rest of the 11 deep dives for 2026.
For access to the portfolio update spreadsheet file, see below the paywall.